Sunshine Financial Partners helps South Florida families protect what they have saved and turn it into a guaranteed paycheck for life—with licensed professionals who educate first and never pressure.
20+ years in Deerfield Beach · Licensed Florida professionals · Hosts of Money Talks on the Blue Couch
Retire with income you can’t outlive.
Sunshine Financial Partners helps South Florida families protect what they have saved and turn it into a guaranteed paycheck for life—with licensed professionals who educate first and never pressure.
Lock in guarantees now and let your savings grow without ever taking a market loss.
Meet the
Fixed Index Annuity
A contract with a highly rated insurance company that guarantees your principal, credits interest linked to a market index with a floor of zero, and can pay you an income for life—tax-deferred, with no annual fees on most contracts.
Guaranteed by the insurer. A down year in the index credits 0%—never a loss.
CDs: FDIC-insured. Stock and bond funds: exposed to every downturn.
Growth
Interest linked to an index, locked in each term and protected going forward.
CDs: a fixed rate. Funds: unlimited upside—and unlimited downside.
Taxes
Tax-deferred. Nothing is owed until you withdraw.
CD interest is taxed every year. Funds are taxed on dividends and gains.
Income for life
Lifetime-income option for you—or you and your spouse.
Not available. Income stops when the money runs out.
Access to funds
Typically 10% per year penalty-free, plus nursing-home and terminal-illness waivers.
CDs: early-withdrawal penalty. Funds: anytime, at whatever the market says they are worth.
Your principal
Fixed index annuity
Guaranteed by the insurer. A down year in the index credits 0%—never a loss.
Bank CDs & market funds
CDs: FDIC-insured. Stock and bond funds: exposed to every downturn.
Growth
Fixed index annuity
Interest linked to an index, locked in each term and protected going forward.
Bank CDs & market funds
CDs: a fixed rate. Funds: unlimited upside—and unlimited downside.
Taxes
Fixed index annuity
Tax-deferred. Nothing is owed until you withdraw.
Bank CDs & market funds
CD interest is taxed every year. Funds are taxed on dividends and gains.
Income for life
Fixed index annuity
Lifetime-income option for you—or you and your spouse.
Bank CDs & market funds
Not available. Income stops when the money runs out.
Access to funds
Fixed index annuity
Typically 10% per year penalty-free, plus nursing-home and terminal-illness waivers.
Bank CDs & market funds
CDs: early-withdrawal penalty. Funds: anytime, at whatever the market says they are worth.
General comparison for education only. Guarantees are backed by the claims-paying ability of the issuing insurer. Surrender charges and IRS penalties may apply to early withdrawals. Not FDIC insured.
Our Personal Pension Plan is
Built to Last
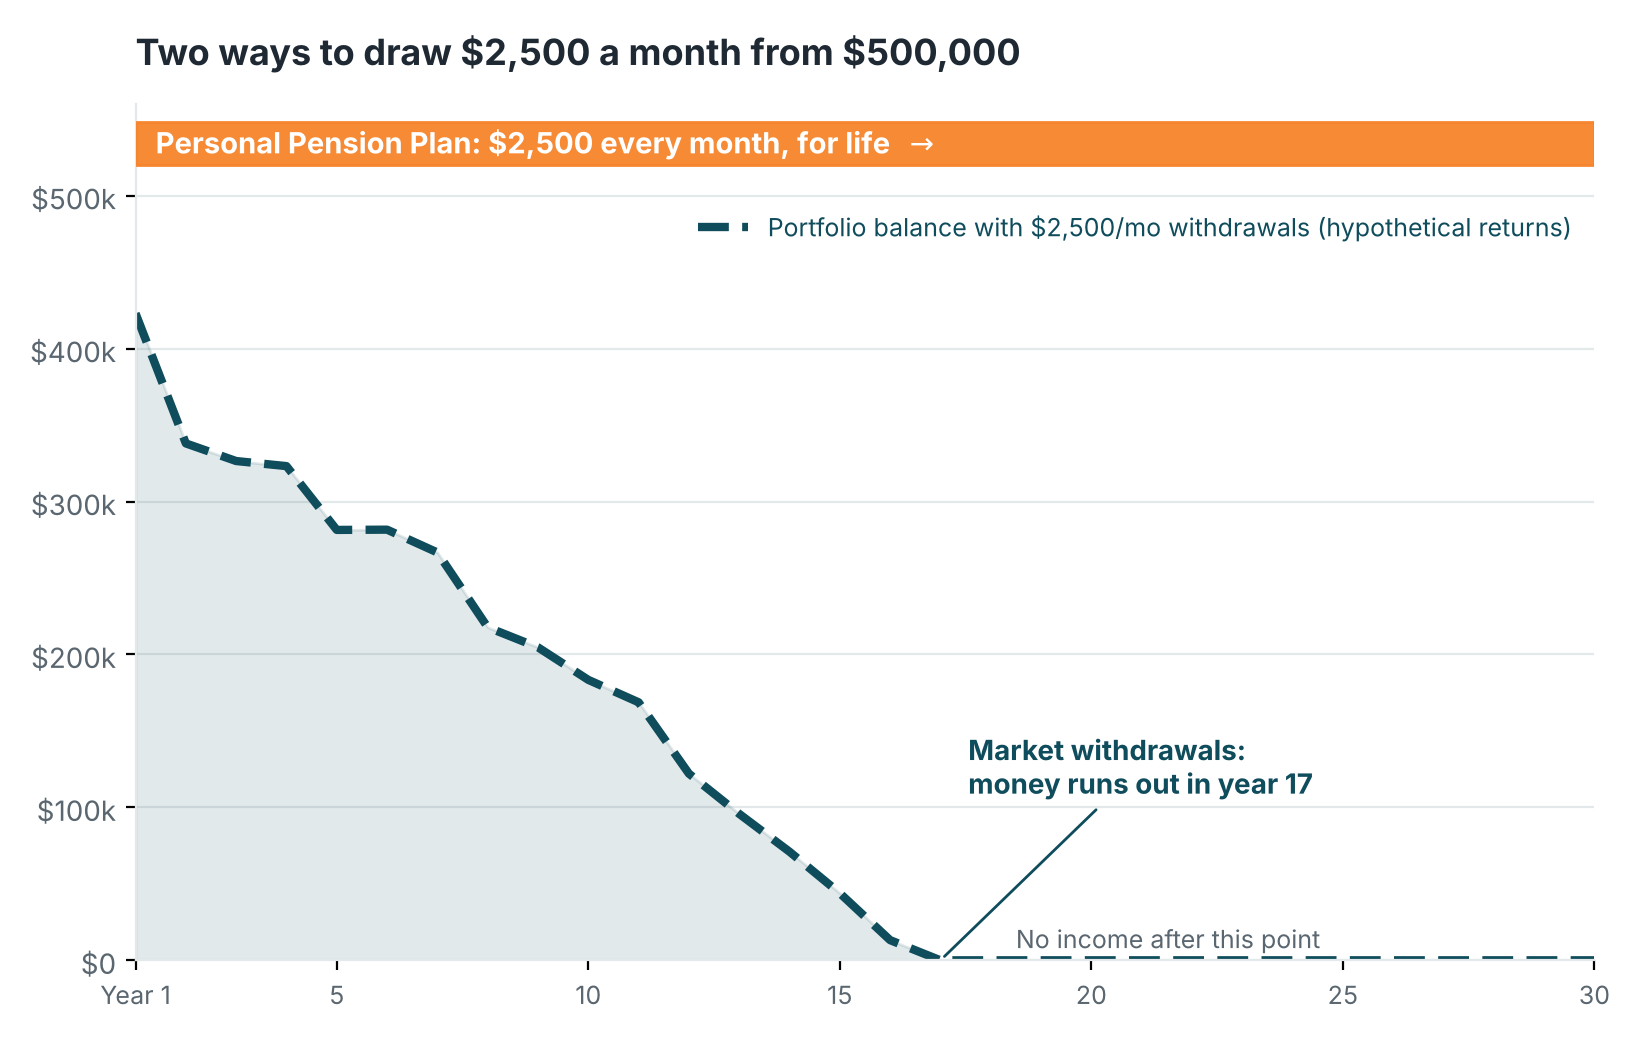
Turn part of your savings into a paycheck that arrives every month, for as long as you live—no matter what the market does.
Get a paycheck for life with the
Personal Pension Plan
We separate your essential expenses from the nice-to-haves, measure the gap Social Security leaves, and fund that gap with guaranteed lifetime income. Cover a spouse, choose when payments start, and keep the rest of your money free to grow.
Guaranteed for your lifetime—or both spouses’ lifetimes
Payments continue no matter what the market does
Optional increasing-income feature to help with inflation
Hypothetical illustration for education only. Not a specific product or a projection of results; assumes $500,000, $2,500 monthly withdrawals and a hypothetical sequence of market returns. Guarantees are subject to the claims-paying ability of the issuing insurer.
Our fixed index annuities are
Made to Make Sense
Everyone’s goals look different, so we design each plan around what matters most to you.
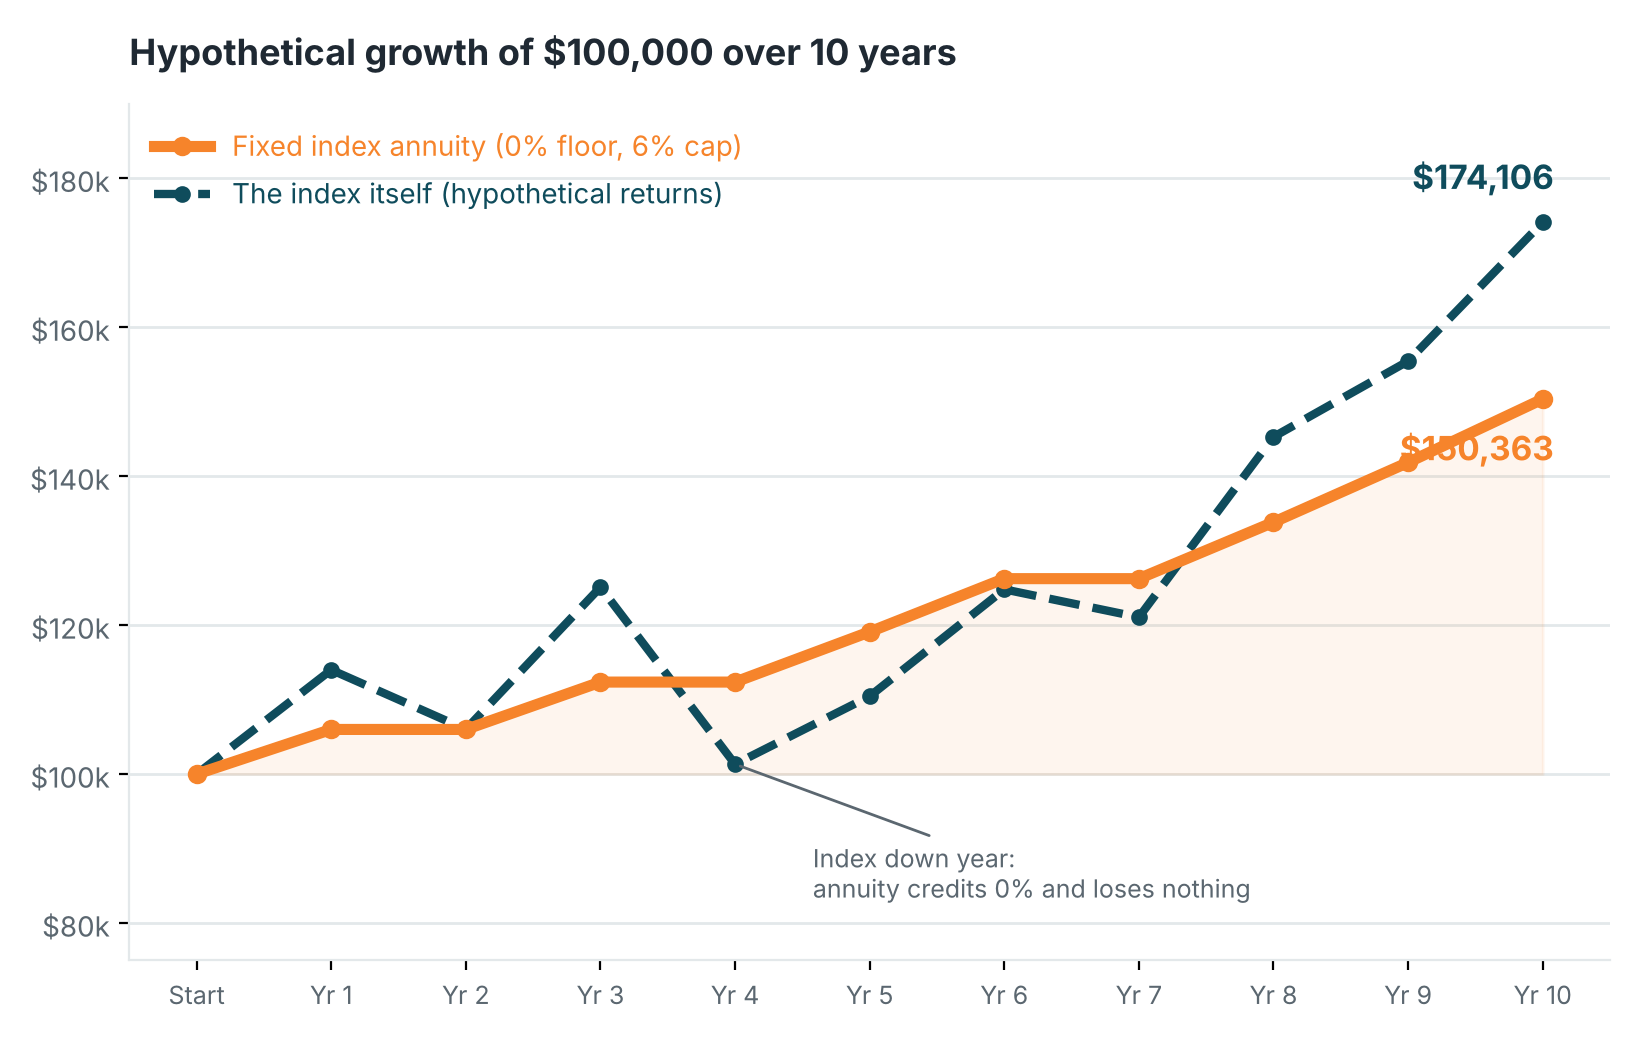
Growth with a floor of zero
Index up: you share in the gain, up to a cap
Index down: you are credited 0% and lose nothing
Gains lock in and become your new floor
Hypothetical illustration for education only. Assumes a 0% floor and 6% annual cap on $100,000 with hypothetical index returns; actual caps, participation rates and crediting methods vary by contract and insurer.
You decide
Built around your goals
How long the income lasts—a set period or your lifetime
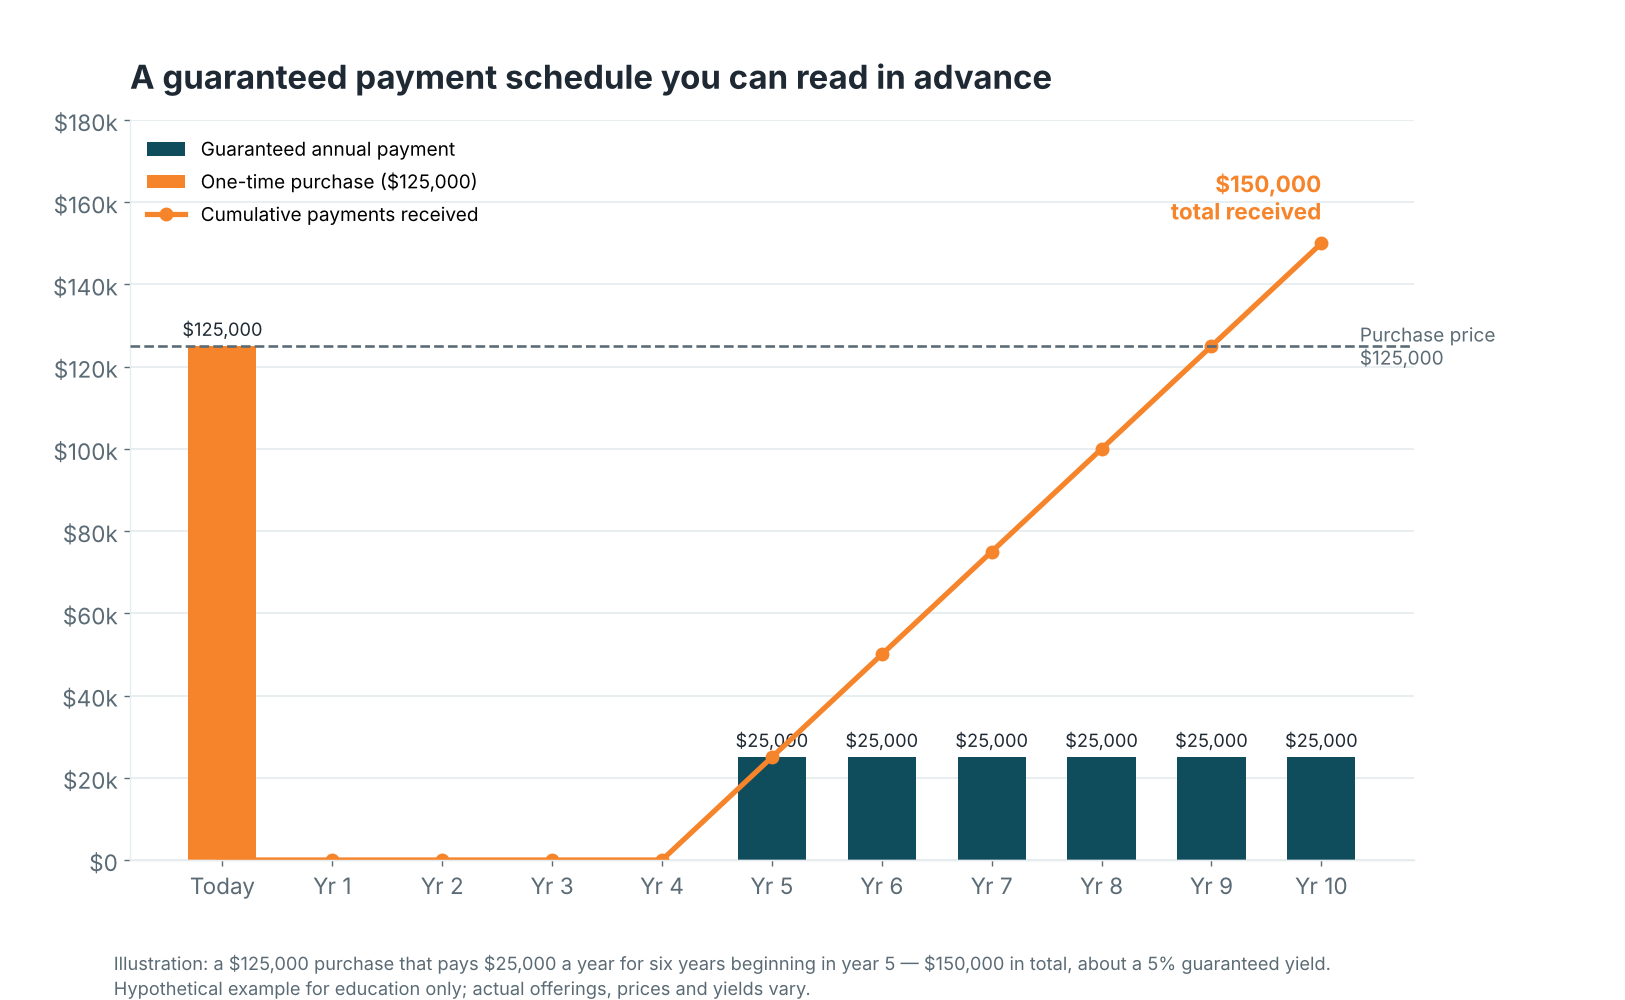
For money you will not need for a few years, a structured settlement turns a lump sum into a guaranteed, dated schedule of payments.
Safe growth, guaranteed by contract
Structured Settlements
Purchase a schedule of future payments—backed by an A-rated life insurer and approved by a court—at a price that locks in roughly 4% to 6% a year. No market risk, no annual fees, and you know every payment date before you buy.
Structured settlement payment rights are purchased in the secondary market through court-approved transfers under state Structured Settlement Protection Acts. Payments are fixed, not inflation-adjusted, and cannot be accelerated or easily resold; guarantees rest on the claims-paying ability of the issuing insurer. Not FDIC insured, not a security, not legal or tax advice. Illustrations are hypothetical and for education only.
How structured settlements compare
Structured settlement
Bank CD
Bonds
Stocks
Rate of return
Fixed by contract—you know the yield before you buy
Fixed, but resets at maturity
Fluctuates with interest rates
Unknown
Market risk
None—payments do not change with markets
None
Yes—prices fall when rates rise
Yes
Income tax
Often tax-free or tax-deferred, depending on the settlement
Taxed every year
Taxed every year
Taxed on dividends and gains
Liquidity
Limited—for money you do not need to touch
Early-withdrawal penalty
Can be sold, at the market price
Can be sold, at the market price
Suited for income planning
Yes—a dated schedule of payments
Short-term savings only
Partly
No
Rate of return
Structured settlement
Fixed by contract—you know the yield before you buy
Bank CD
Fixed, but resets at maturity
Bonds
Fluctuates with interest rates
Stocks
Unknown
Market risk
Structured settlement
None—payments do not change with markets
Bank CD
None
Bonds
Yes—prices fall when rates rise
Stocks
Yes
Income tax
Structured settlement
Often tax-free or tax-deferred, depending on the settlement
Bank CD
Taxed every year
Bonds
Taxed every year
Stocks
Taxed on dividends and gains
Liquidity
Structured settlement
Limited—for money you do not need to touch
Bank CD
Early-withdrawal penalty
Bonds
Can be sold, at the market price
Stocks
Can be sold, at the market price
Suited for income planning
Structured settlement
Yes—a dated schedule of payments
Bank CD
Short-term savings only
Bonds
Partly
Stocks
No
Structured settlement payment rights are purchased in the secondary market through court-approved transfers under state Structured Settlement Protection Acts. Payments are fixed, not inflation-adjusted, and cannot be accelerated or easily resold; guarantees rest on the claims-paying ability of the issuing insurer. Not FDIC insured, not a security, not legal or tax advice. Illustrations are hypothetical and for education only.
Planning with
Certainty
The best retirement plans are built on clarity: what is guaranteed, what is at risk, and what happens if life does not go to plan.
A written plan with guarantees
You leave with a plan on paper showing exactly which income is guaranteed and for how long.
Here to educate, not to sell
Every option explained in plain English, with the trade-offs, before any recommendation.
Licensed Florida professionals
Three partners with 20+ years each, members of the Safe Money Places® Agent Network.
Reviews every year
Retirement lasts decades. We revisit the plan with you annually, for as long as you need us.
Our partners do not work from a script. Ask about income, Social Security, long-term care or leaving a legacy and you will get a straight answer from a licensed professional—never a pitch.
Every week our partners sit down on the blue couch in our Deerfield Beach office for Money Talks on the Blue Couch—plain-English conversations and guest interviews about retirement income, Social Security, annuities and protecting what you have saved. Our partners also host Safe Money Radio in South Florida. Watch the latest episode, then bring your question to a free review.
Fixed and fixed index annuities are insurance contracts: the issuing company guarantees your principal and a minimum interest rate, and Florida’s Life & Health Insurance Guaranty Association adds a further layer of protection within statutory limits. They are not FDIC-insured and are not stock-market investments.
Are annuities low-risk?
Fixed annuities are among the lowest-risk savings vehicles available to retirees because the insurance company—not you—bears the market risk. Variable annuities are different: your value rises and falls with the market.
What is a guaranteed paycheck for life?
A lifetime-income option converts part of your savings into payments that continue for as long as you (or you and your spouse) live, no matter how long that is or what the market does.
How much should I be saving for retirement?
It depends on the income you want and what Social Security and any pension already provide. Our income-gap analysis puts a real number on it instead of a rule of thumb.
How do I get started with Sunshine Financial Partners?
Request a free, no-obligation income review. We meet in Deerfield Beach or by phone, listen first, and show you where you stand before any product is discussed.
Free consumer’s guide
Annuities: Safe Money Products that Grow & Preserve Wealth
Tell us where to send it and we’ll email the PDF right away. No obligation, no follow-up pressure.